


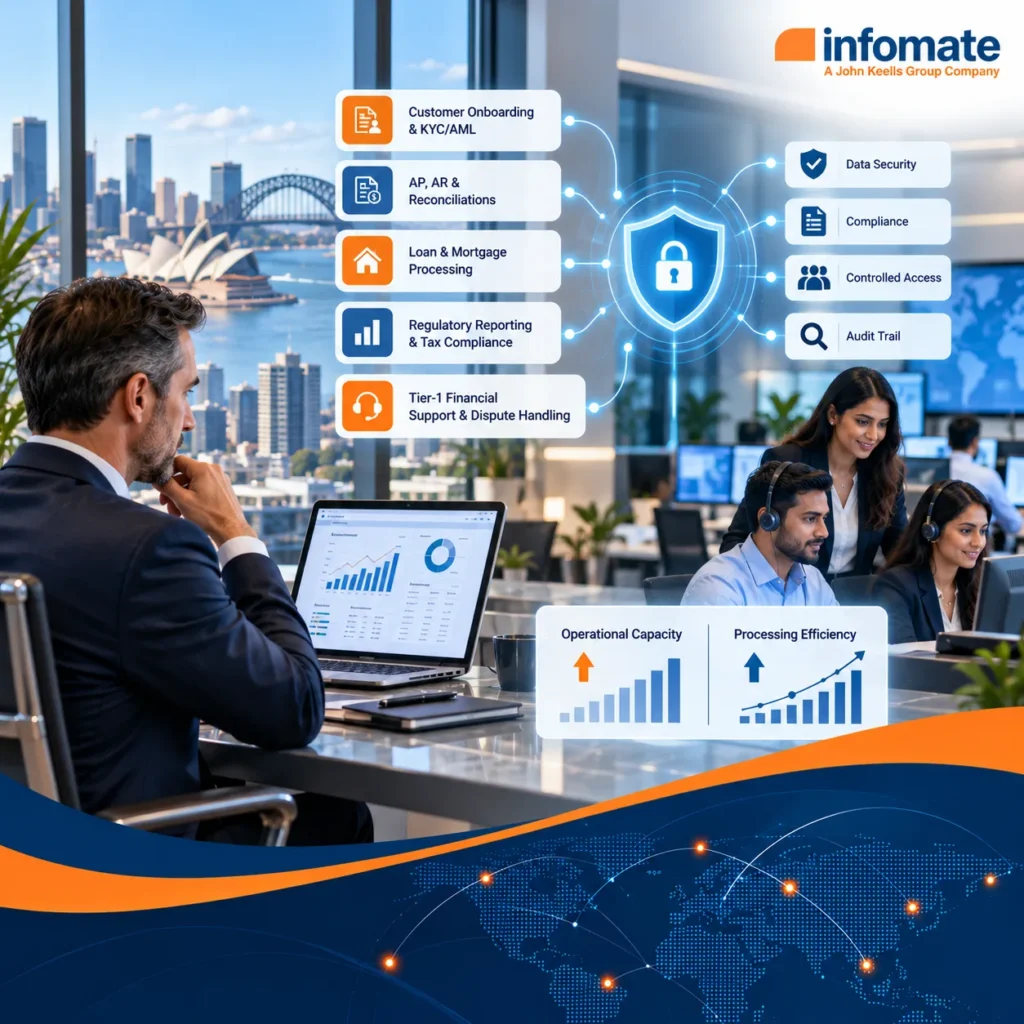
Financial services compliance teams are busier than ever.
Across major markets, regulators are tightening anti-money laundering (AML) rules, raising the bar on operational resilience, and closely scrutinizing how firms manage outside providers. Meanwhile, financial crime is not slowing down. The amount of money laundered globally each year is estimated at $800 billion to $2 trillion, or 2–5% of global GDP, according to the United Nations Office on Drugs and Crime.
The workload keeps growing. Most operations teams don’t.
With year-end close on the way and new EU AML rules arriving in 2027, the next few months are the best time to free up capacity, before the pressure peaks.
If your people are already stretched between onboarding checks, month-end reconciliations, reporting and customer queries, hiring alone won’t fix it. You need more capacity, without more risk.
That is where BPO for financial services comes in.
Quick answer: BPO for financial services means outsourcing selected high-volume, rules-based work, such as KYC document checks, reconciliations, loan administration, reporting preparation and Tier-1 customer support, to a specialist external team. Your organisation keeps control of decisions, approvals, risk and accountability.
The evidence at a glance
| What the official data says | Source |
|---|---|
| An estimated $800 billion–$2 trillion is laundered globally each year (2–5% of global GDP) | United Nations Office on Drugs and Crime |
| The EU’s single AML rulebook applies from 2027 | European Commission |
| DORA has applied to EU financial firms since 17 January 2025 | EIOPA |
| UK regulators say there is “more work to do” on third-party vulnerabilities (March 2026) | Financial Conduct Authority |
What’s Changed: Why Financial Services Teams Are Under Pressure
1. AML rules are getting tougher around the world
The EU has adopted a new AML package that includes a single AML rulebook applying from 2027 and a new EU Anti-Money Laundering Authority (AMLA) based in Frankfurt. In Australia, major AML/CTF reforms took effect on 31 March 2026. Other markets are moving in the same direction, guided by the Financial Action Task Force (FATF), the global standard-setter for AML. More checks, more records and more reviews all mean more operational work.
2. Operational resilience is now a regulatory requirement
The EU’s Digital Operational Resilience Act (DORA) has applied since 17 January 2025, including rules on managing ICT third-party providers. In the UK, the FCA’s operational resilience rules required in-scope firms to be able to stay within impact tolerances for their important business services by 31 March 2025. In Australia, APRA’s CPS 230 has applied since 1 July 2025 and covers risks from material service providers.
Regulators are also clear that the work isn’t finished. In its March 2026 review, the FCA said firms are testing their third-party providers more rigorously, but “there is more work to do on identifying, assessing and remediating third-party vulnerabilities.” At a global level, the Financial Stability Board has published a toolkit to help financial institutions manage third-party risk across the full life of a provider relationship.
What this means for you: the right outsourcing partner must be able to prove its controls, support your testing and give you full visibility.
3. Customers expect faster, always-on service
Digital banking and instant payments mean customers expect quick answers at any hour. Fraud adds to the pressure, because every suspicious transaction can mean a call, a dispute and a case to document.
The bottom line: you need more processing capacity, but any outsourcing partner must strengthen your controls, not weaken them.
Not sure which processes you could safely outsource? Infomate can review your current workflows and show you where extra capacity would make the biggest difference. Book a free operations review.
1. Customer Onboarding and KYC/AML: Scale the Checks, Not the Risk
As AML rules tighten, onboarding queues are getting longer.
Every new account can involve identity documents, verification, sanctions and PEP screening, beneficial ownership checks and records to maintain. Much of this is process-heavy, which makes selected parts suitable for outsourcing.
A BPO team can support document intake, identity verification steps, sanctions and PEP screening, beneficial ownership checks and preparing cases for your compliance team to review. The Financial Action Task Force’s guidance on beneficial ownership explains why identifying the real owners behind a customer matters for financial crime controls.
But remember:
You can outsource parts of the process. You can’t outsource accountability.
Your organisation still needs clear escalation rules, internal oversight and alignment with your AML/CTF program. Security should start the moment customer information enters the workflow: encrypted uploads, controlled storage, role-based access and full audit trails.
The result: your compliance specialists spend less time on routine checks and more time on exceptions and high-risk cases.
2. AP, AR and Reconciliations: Take the Volume Off Your Finance Team
Ask any finance team where month-end goes, and you’ll hear the same list:
Invoices. Matching. Reconciliations. Payment admin. Exceptions. Follow-ups.
None of it is unimportant. The problem is the volume. As transactions grow, repetitive processing eats into time that could be spent on cash flow analysis and decision support.
Infomate’s finance and accounting outsourcing services can take on invoice matching, accounts payable, accounts receivable, bank reconciliations and ledger reconciliations within a structured workflow.
Efficiency must not cost you control. If an outsourced team touches payment processes, be clear on:
Who can create a payment? Who approves it? Who releases it? What can each person access? Can every action be traced?
Dual authorisation, segregation of duties, role-based access and detailed logs are essential. If a provider offers a SOC 2 Type II report, check what was assessed, over what period and whether your processes were in scope.
3. Loan and Mortgage Processing: Clear the Admin Bottleneck
A lot of work happens before an underwriter makes a decision.
Documents need collecting and indexing. Income and employment details need checking. Credit information needs compiling. Applications need completeness checks.
These structured steps are a natural fit for BPO for financial services. The provider handles the defined admin stages, and your authorised team keeps the credit decisions.
That separation also applies to technology. If lending data is processed offshore or in the cloud, know where it is stored, who can access it and whether any rules restrict cross-border access. Data protection laws such as the EU’s GDPR set rules for international data transfers, and many other countries have similar requirements.
Data residency is much easier to solve before transition than after go-live.
4. Regulatory Reporting and Tax: Make Your Numbers Easy to Defend
A regulatory deadline is the worst time to find three teams working from three versions of the same spreadsheet.
BPO teams can support transaction-log preparation, GST/VAT tracking, audit schedules, tax documentation, risk-reporting inputs and data used in IFRS-aligned reporting. The IFRS Foundation notes that more than 140 jurisdictions require IFRS Accounting Standards for all or most publicly listed companies.
The real value isn’t just someone else preparing the data. It is a repeatable process around it, with version control, approvals and audit trails that answer:
Where did this number come from? Who changed it? Who checked it? Which version was reported?
5. Tier-1 Financial Support: Keep Routine Queries Moving 24/7
Customers don’t keep office hours. A card transaction gets questioned late at night. A balance query comes in on Sunday. A chargeback arrives when your team is already full.
Fraud is a growing concern. In the US alone, consumers reported $15.9 billion in fraud losses in 2025, according to the Federal Trade Commission. That makes fast and consistent first-line support more important than ever.
An external customer support and call centre team can handle routine enquiries, transaction help, initial dispute queries and basic card-fraud questions, escalating anything that needs a specialist.
Security must follow the work. Where card data is involved, the PCI Data Security Standard applies. Depending on the workflow, that can mean encrypted communications, secure virtual desktops, data masking, controlled devices and clean-desk rules.
Quick Self-Check: Is It Time to Outsource?
If you answer “yes” to two or more of these, it is worth a conversation:
Ticked two or more? Talk to Infomate about a no-obligation assessment of your finance and operations workflows. Contact our team.
The Real Value of BPO: Capacity Without Losing Control
The question isn’t just “How much can we save?”
It should be: “How much capacity can we add without creating more risk or permanent complexity?”
A well-designed BPO model can support 24/7 processing across time zones and add capacity during month-end, onboarding spikes or high-volume periods. There may be cost benefits too, but savings depend on the process, technology, transition effort and governance needed. There is no single number that fits everyone.
Security deserves the same practical thinking. Standards and controls such as ISO/IEC 27001, SOC 2 Type II, PCI DSS, encryption, secure VDI, role-based access and audit logging all help build a stronger control environment. Infomate is ISO 27001 certified. Read more on why information security rigour matters.
But a certificate on the wall doesn’t secure your operation.
The controls need to work every day.
Infomate was also included in Everest Group’s 2026 PEAK Matrix assessments for Integrated Finance and Accounting Services, including the mid-market assessment.
Before You Outsource, Get These Four Things Right
1. Check security before price
Review certifications, audit reports, access controls, incident procedures and business continuity plans. Don’t stop at “Are you certified?” Ask which systems and locations are covered, and how controls are tested. Make sure the arrangement fits the third-party and outsourcing rules that apply to you, such as DORA, the UK operational resilience rules or APRA’s CPS 230.
2. Start small
A 60–90 day pilot on a clear process, such as document indexing or bank reconciliation, tells you more than any presentation. Set your baseline first so you can measure accuracy, turnaround and impact.
3. Make your SLA measurable
Define turnaround times, accuracy targets, availability, escalation steps, compliance expectations and incident response. An SLA only works when both sides know what success looks like.
4. Govern the relationship
Schedule control reviews, keep audit access, review user permissions regularly and spell out data residency and protection requirements. See how Infomate manages this through its transition and delivery process.
Proven in Finance Operations
Infomate supports finance teams across Australia, the UK, the Nordic region and North America. For a global client headquartered in Europe, Infomate took on accounts payable, accounts receivable, bank reconciliation and financial planning support, and the engagement doubled in size in its first year. A Norwegian accounting firm has worked with Infomate since 2010.
Frequently asked questions
Scale What Should Scale. Keep Control of What Matters.
Tougher AML rules, operational resilience requirements and rising customer expectations don’t have to mean an ever-growing operations team.
The right BPO for financial services model adds capacity for onboarding, finance operations, lending admin, reporting and customer support, while keeping security, compliance and governance at the centre.
Infomate helps financial services businesses grow without losing visibility over the processes and data that matter most.
Book your free operations review with Infomate and find out which workflows you could safely outsource before the next compliance deadline.